MTUM relative to QUAL crossed below its 13-week average this week, and the ratio fell 7.5%.
The iShares MSCI USA Quality Factor ETF (QUAL) and the iShares MSCI USA Momentum Factor ETF (MTUM) both track US stocks: QUAL those with high return on equity, stable earnings and low debt, MTUM those with relatively high price momentum. This page compares their price, risk and relative strength, refreshed weekly.
Performance & Risk Snapshot
QUAL vs MTUM · adjusted close data, as of October 16, 2026
| Metric | QUAL
Quality factor | MTUM
Momentum factor |
|---|
| Total return |
| 1 week | −1.0% | −8.4% |
| 1 month | +2.7% | −4.2% |
| 3 months | +3.9% | −2.9% |
| 1 year | +17.2% | +15.8% |
| 3 years annualized | +19.6% | +28.5% |
| 5 years annualized | +12.4% | +11.8% |
| Full period annualized, since 2013 | +13.7% | +15.0% |
| Risk (trailing 3Y) |
| Volatility annualized, Yang–Zhang | 14.6% | 23.4% |
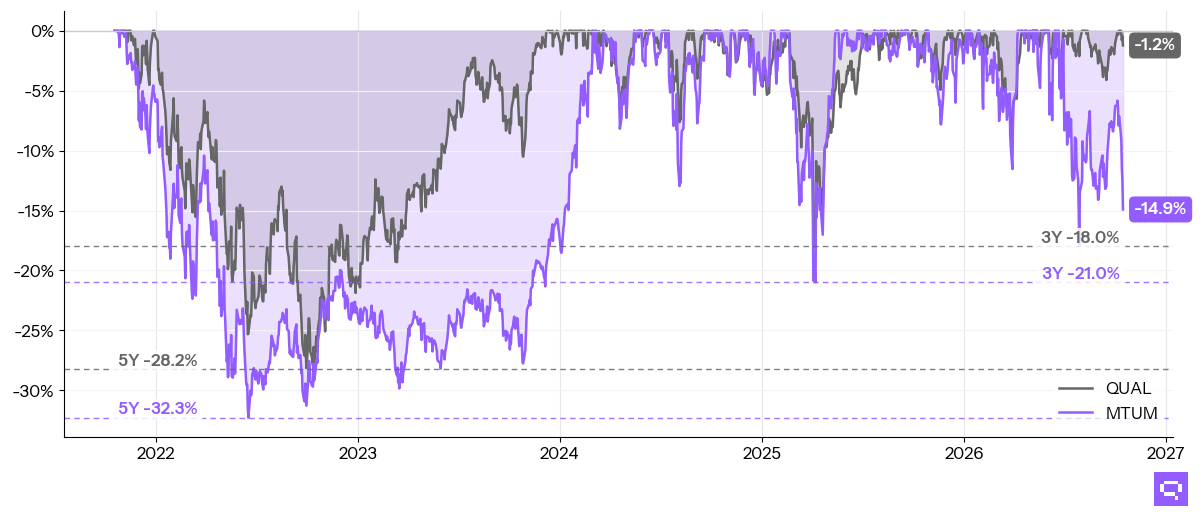
| Max drawdown | −18.0% | −21.0% |
| Sharpe ratio | 1.04 | 1.04 |
| Sortino ratio | 1.55 | 1.50 |
| Calmar ratio | 1.09 | 1.36 |
| Trend (price vs its own SMA) |
| Price vs 10-month SMA regime | Above | Above |
| Price vs 13-week SMA intermediate | Above | Below |
| Cost & income |
| Expense ratio | 0.150% | 0.150% |
| Dividend yield TTM | 0.8% | 0.6% |
| Assets under management | $49B | $20B |
| Relationship |
| Correlation to each other daily, 3Y | 0.80 |
| MTUM beta to QUAL | 1.28 |
| Beta to SPY daily, 3Y | 0.92 | 1.27 |
| Top-10 holdings weight | 45.9% | 35.1% |
How to read this. Over the trailing 3Y, QUAL and MTUM posted a correlation of 0.80. The snapshot table shows 14.6% volatility for QUAL and 23.4% for MTUM, with three-year max drawdowns of 18.0% and 21.0%.
This week
QUAL fell 1.0% this week and MTUM 8.4%. QUAL trades above its regime and intermediate trends; MTUM trades above its regime trend and below its intermediate trend. MTUM relative to QUAL fell 7.5%, crossed below its 13-week average and sits in the lower half of its 12-month range. QUAL is 1.2% below its October 12, 2026 high; MTUM is 14.9% below its June 22, 2026 high.
MTUM/QUAL ratio
1.303
12-mo range 1.218 to 1.600
Ratio, 1 week
−7.5%
week over week
QUAL from high
−1.2%
from its October 12, 2026 high
MTUM from high
−14.9%
from its June 22, 2026 high
Concentration
QUAL carries 45.9% in its top 10, led by Technology and Communication Services names. MTUM carries 35.1% in its top 10, led by Technology and Healthcare names.
Top 10 Holdings & Weights
Share of fund assets in each of the ten largest positions
QUAL top 10
Top 10 = 45.9% of the fund
MSFT8.04%
AAPL7.05%
NVDA6.68%
META4.82%
LLY3.73%
TJX3.60%
V3.42%
LRCX3.41%
AMAT2.67%
KLAC2.48%
MTUM top 10
Top 10 = 35.1% of the fund
AMD6.28%
MU4.75%
INTC3.99%
CSCO3.56%
JNJ3.20%
GOOGL2.85%
AMAT2.75%
PANW2.64%
XOM2.61%
SNDK2.50%
Growth of $100
Since July 18, 2013, QUAL compounded at 13.7% a year and MTUM at 15.0%.
Max historyMONTHLY · MAX HISTORY
MTUM / QUAL Ratio
The relative-strength ratio tracks MTUM relative to QUAL, and a rising line means MTUM is leading QUAL. The ratio sits below both its 10-month and 13-week moving averages, and the near-term trend favors QUAL.
Max historyMONTHLY · 10M SMA
Last 5 yearsWEEKLY · 13W SMA
Where the ratio stands
Full-range percentile
69th
MTUM/QUAL full history
5-year percentile
81st
within last 5 years
Z-score
0.68
vs full-history mean
The ratio stands in the 69th percentile of full history and the 81st percentile of the past five years. Its z-score is 0.68.
Rolling Correlation (MTUM vs QUAL)
The latest 126-day correlation between QUAL and MTUM is 0.59.
MTUM – QUAL daily-return correlationWEEKLY · 5Y · 126D WINDOW
Rolling Volatility
At the latest 126-day reading, QUAL shows 11.5% volatility and MTUM 33.0%.
Annualized realized volatility (Yang–Zhang)WEEKLY · 5Y · 126D WINDOW
Rolling Beta to the S&P 500
At the latest 126-day beta to the S&P 500, QUAL reads 0.79 and MTUM 1.87. A fund at 1.00 moves with the index; the further a reading sits from 1.00 the more the fund's path separates from the index.
QUAL and MTUM beta to SPY (reference line at 1.00)WEEKLY · 5Y · 126D WINDOW
Drawdown
Over the trailing three years, QUAL posted a max drawdown of 18.0% and MTUM 21.0%.
Drawdown from prior peak (dashed lines mark the 3Y and 5Y max drawdown)DAILY · 5Y
Time underwater
QUAL longest underwater
23 mo
2021 to 2023
MTUM longest underwater
28 mo
2021 to 2024
QUAL spent 23 months (2021 to 2023) below its prior peak, and MTUM 28 months (2021 to 2024).
Upside / Downside Capture
Since July 18, 2013, MTUM captured 101% of QUAL's up-market monthly moves and 93% of its down-market monthly moves. The capture ratio is 1.10.
Upside capture
101%
MTUM vs QUAL, up months, since Jul 2013
Downside capture
93%
MTUM vs QUAL, down months, since Jul 2013
Capture ratio
1.10
up ÷ down, since Jul 2013
Beyond the price
What each index screens on. MTUM ranks stocks on trailing risk-adjusted price performance, so its book turns over as leadership changes. QUAL ranks on return on equity, debt-to-equity, and earnings variability, so its book changes when the reported financials do. Rebalancing. Both indices are reviewed semi-annually, and the momentum index adds conditional rebalances after volatility spikes, which is where the turnover gap comes from. Cost. Both charge 0.150%. Volatility. Over the trailing three years MTUM realized 23.4% against QUAL's 14.6%.
The Bottom Line
QUAL pairs a steadier path with a quality tilt, and MTUM brings a faster-moving momentum profile. The current trend read favors QUAL after MTUM fell 8.4% for the week and slipped below its 13-week trend line.
Where these fit at Quantlake
Quantlake's Smart model portfolios allocate across factors rather than holding one factor outright, because momentum and quality lead in different regimes. Discover which model aligns with your Behavioral Risk profile.
Related
Definitions
Returns and risk
Total return: price change plus reinvested dividends, using adjusted-close prices.
Annualized volatility (Yang–Zhang): spread of returns scaled to one year; the Yang–Zhang estimator uses the open, high, low, and close of each bar, so it is more efficient than a close-to-close estimate.
Maximum drawdown: the largest peak-to-trough decline over the period.
Risk-adjusted ratios
Sharpe ratio: annualized return above T-bills (BIL) per unit of total volatility.
Sortino ratio: like Sharpe, but divides by the volatility of returns below the T-bill rate.
Calmar ratio: annualized return divided by the worst drawdown.
Trend and relationship
Trend filters (regime / intermediate / tactical): moving-average timeframes in the Quantlake taxonomy: the 10-month average marks the regime (long-term) trend, the 13-week the intermediate trend, and the 20-day the tactical trend. A price or ratio above its average is an uptrend on that horizon, below it a downtrend.
Correlation: co-movement between two return streams, from −1 to +1.
Beta: sensitivity to a reference; a beta of 2 moves about twice a given reference move.
Relative-strength ratio: one fund's price divided by another; a rising ratio means the numerator is outperforming.
Upside / downside capture: the share of the benchmark's up (down) moves the fund reproduces; a capture ratio above 1 means it kept more of the up moves than of the down moves.
Romain Gandon
CEO, Quantlake
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice. Past performance is not indicative of future results.