ETF Sharpe Ratio: How to Compare ETFs by Risk-Adjusted Return
The Sharpe ratio scores an investment by its return per unit of risk, so ETFs with different volatility can be compared fairly. What counts as a good reading, how it differs from Sortino, and where 2 ETF groups sit today.
The Sharpe ratio prices risk, not return
The Sharpe ratio scores an investment by its return per unit of risk. It takes the return earned above a risk-free rate, the excess return, and divides it by volatility. Two funds with different risk levels can then be compared on the same footing: not on who returned more, but on who returned more for the risk taken.
Return: the annualized gain. Risk-free rate: the yield on short government bills. Volatility: the standard deviation of returns, annualized.
A higher Sharpe means more reward per unit of risk. Two rules keep the comparison fair: use the same window and the same frequency for every fund, and annualize consistently. A daily Sharpe is scaled to annual terms by multiplying by the square root of about 252 trading days.
Below 1 is sub-par, above 2 is rare
| Sharpe range | Reading |
|---|---|
| Below 0 | The asset trailed cash. Extra risk was not rewarded over the window. |
| 0 to 1 | Sub-par. Positive excess return, but modest for the volatility taken. |
| 1 to 2 | Good. A solid unit of excess return per unit of risk. |
| Above 2 | Strong. Rare to sustain; often reflects a short or unusually calm window. |
Treat these as rules of thumb, not thresholds. A Sharpe above 2 is uncommon over a full cycle; it usually reflects a short or unusually calm sample rather than a durable edge. A negative Sharpe is unambiguous: the asset trailed cash, so its risk went unrewarded over the window.
Four things the ratio cannot see
Its strength is that one number ranks funds, sleeves, or whole portfolios on risk-adjusted terms from nothing more than daily prices. Its blind spots matter just as much:
- It treats upside and downside volatility alike. A fund penalized for large gains scores no better than one penalized for large losses, which few investors actually experience the same way.
- It assumes returns are roughly normal. Fat tails and option-like payoffs can show a flattering Sharpe while hiding rare, deep losses.
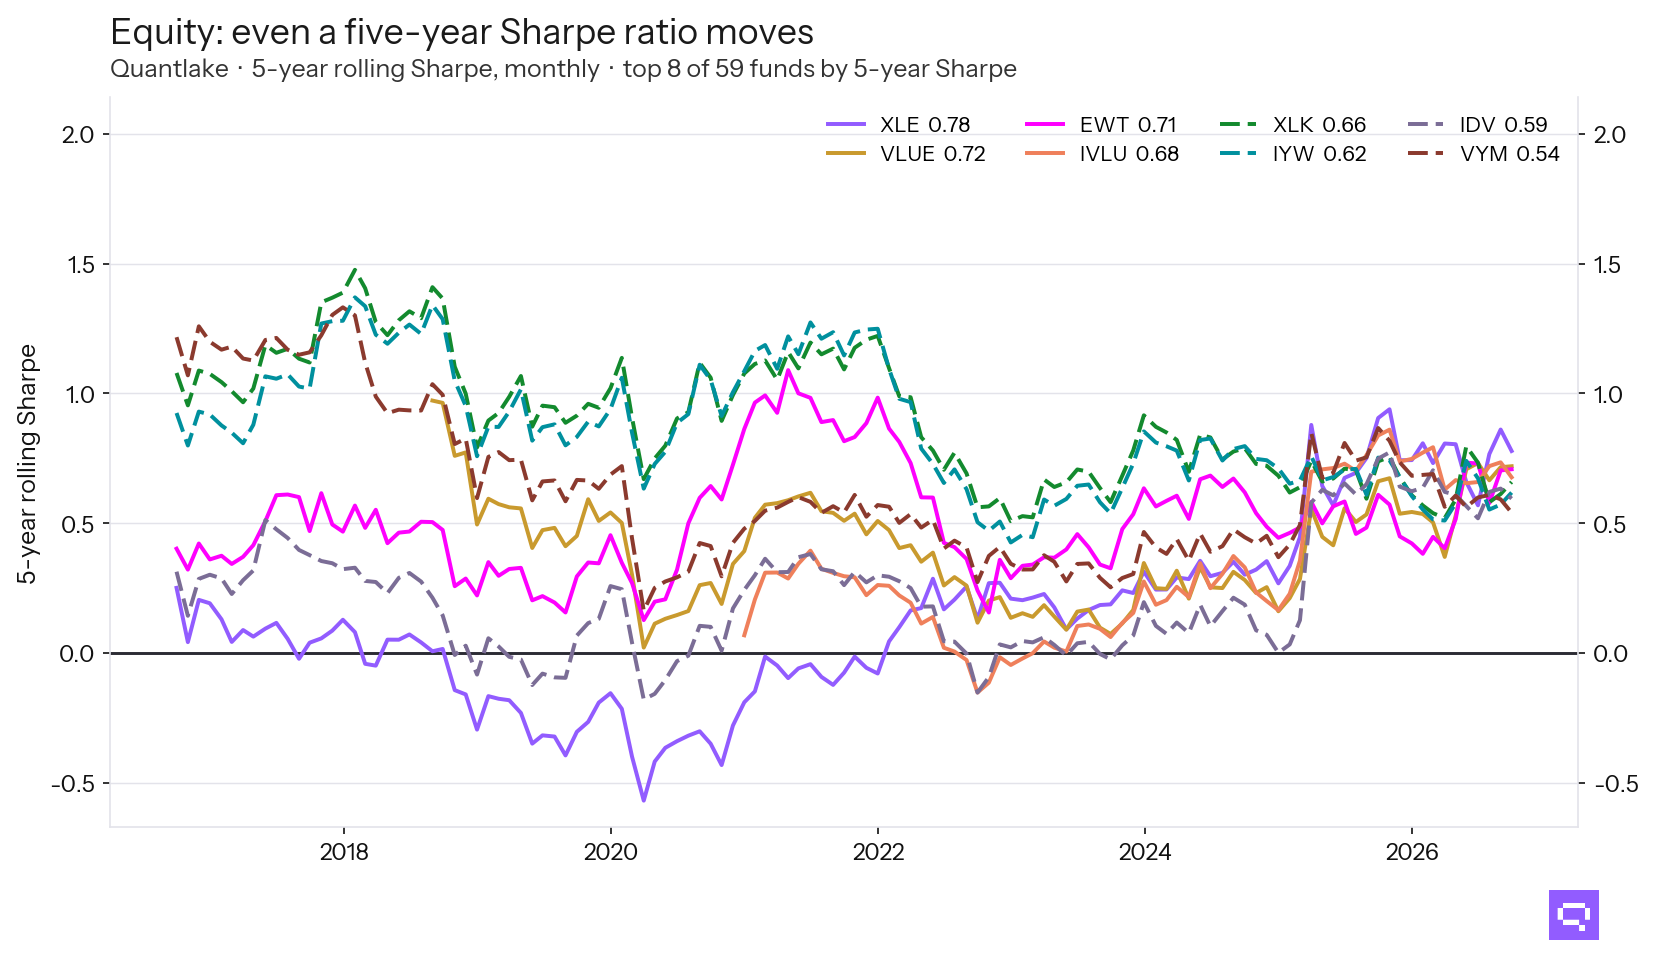
- It moves with the window and the risk-free rate. The same fund reads strong or weak depending on the period measured and the rate subtracted, so the inputs are never incidental.
- Smoothed returns inflate it. Illiquid or appraisal-priced assets understate volatility, which lifts the ratio artificially.
Sortino, Calmar and Treynor each answer a different question
The Sharpe ratio is a starting point, not a verdict. These companions cover what it leaves out:
| Measure | Definition | What it adds |
|---|---|---|
| Sortino | Excess return ÷ downside deviation | Penalizes only losses, not upside swings. |
| Calmar | Annualized return ÷ worst drawdown | Ties reward to the deepest peak-to-trough loss. |
| Treynor | Excess return ÷ beta | Rewards return per unit of market risk, not total risk. |
| Max drawdown | Largest peak-to-trough decline | The loss a holder actually had to sit through. |
Quantlake reports the Sharpe ratio alongside the Sortino ratio and maximum drawdown for its model portfolios. The live figures below use close-to-close volatility, the textbook input to the formula; our production estimates use the Yang–Zhang method, which reads each day's open, high, low, and close for a more efficient measure. The SPY vs RSP and GLD vs GDX pages put these three side by side on a single pair.
Why the literature settled on risk-adjusted measurement
Risk-adjusted measurement is the standard the literature settled on, not a house convention. Bodie, Kane, and Marcus treat ratios like the Sharpe ratio as the baseline for comparing portfolios in Investments (12th edition, 2021). Fama and French (1992) showed that market risk, company size, and value drive the cross-section of returns, which is exactly why raw return is an incomplete score: two funds can post the same return while loading very differently on risk. Dividing return by risk is what makes them comparable.
Sharpe ratios across the market right now
The Sharpe ratios below are computed from real prices over a trailing 5-year window, against a 3.9% risk-free rate (BIL T-bill proxy, annualised over the same 5-year window). This block refreshes monthly. Points on a steeper reference line earn more return per unit of risk.
Cross-asset ETFs
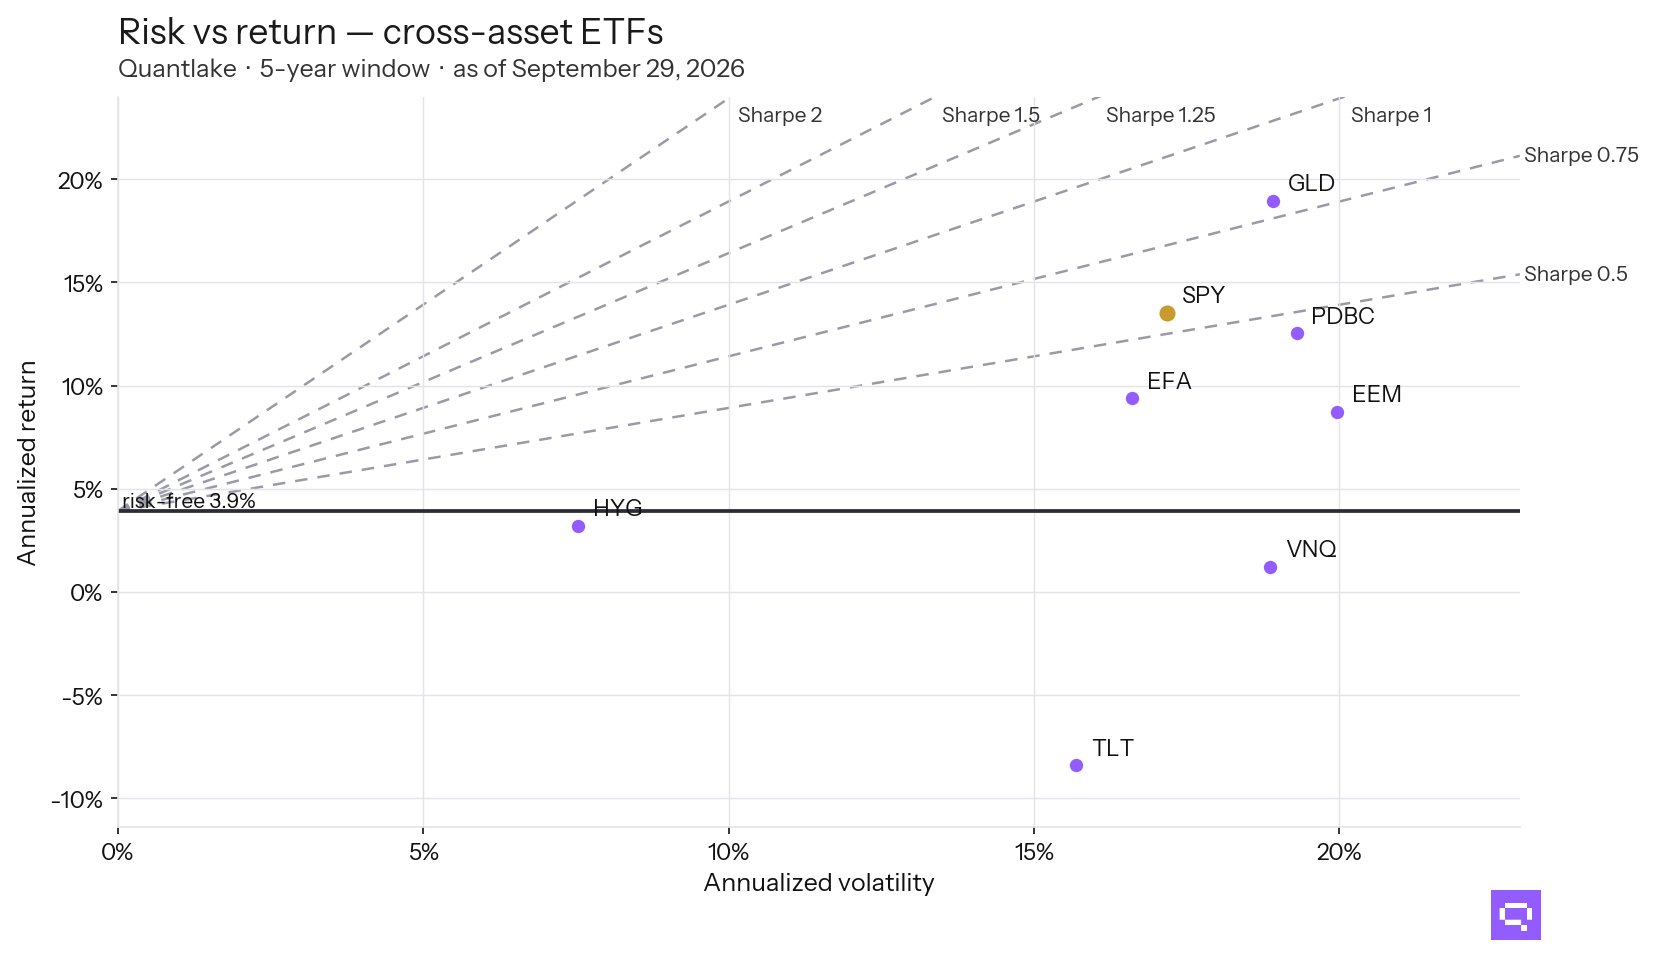
Over the trailing 5 years, GLD (Gold) led the cross-asset ETFs on risk-adjusted return with a 0.80 Sharpe, against SPY's 0.56, and it also holds the best Sortino at 1.12.
US sector ETFs
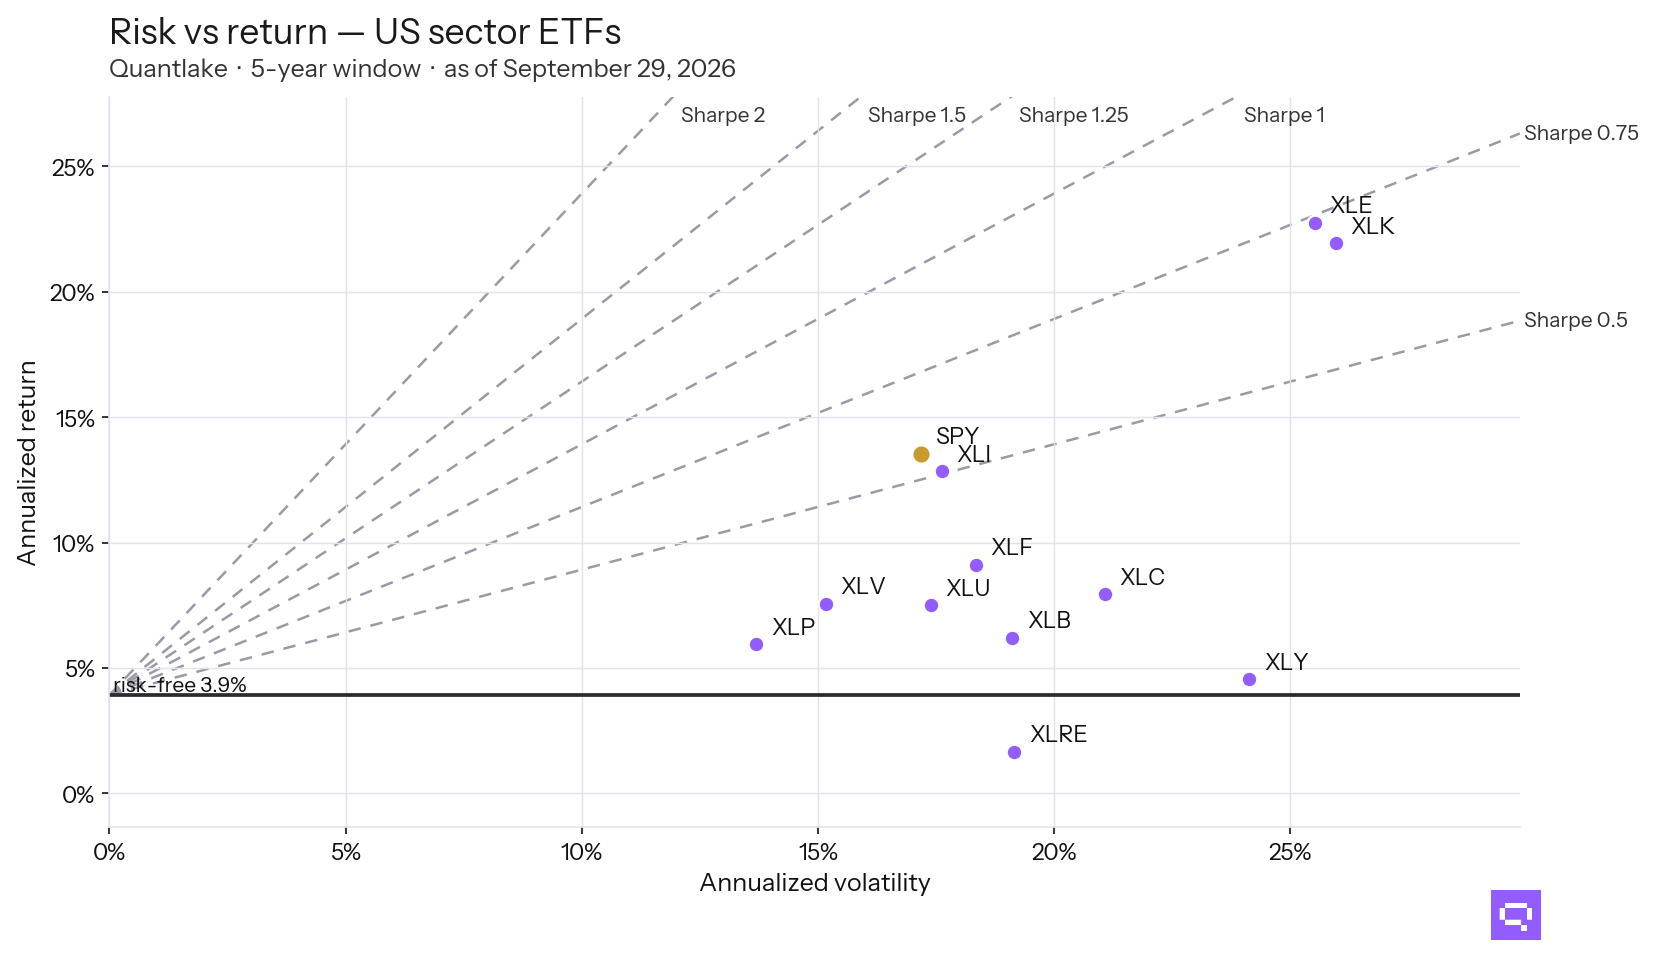
Over the trailing 5 years, XLE (Energy) led the US sector ETFs on risk-adjusted return with a 0.74 Sharpe, against SPY's 0.56, and it also holds the best Sortino at 1.03.
Frequently asked questions
Related
- SPY vs RSP: cap-weight vs equal-weight
- GLD vs GDX: bullion vs miners
- MTUM vs QUAL: momentum vs quality
- ETF trend metrics explained
- Compound interest calculator with volatility, inflation and fees