Daily Movers: Energy XLE Slid 2.88%
Wednesday registered a selective disinflation tilt. Energy XLE set the downside tone as inflation-linked and hard-asset exposures softened. Financials XLF fell 1.62%, TIPS TIP dropped 0.38%, Gold Miners GDX lost 1.41%, and Minimum Volatility USMV declined 0.70%. Taiwan EWT rose 1.62%, Preferred Stock PFF added 0.23%, International Bonds BNDX gained 0.21%, and Biotech IBB edged up 0.20%.
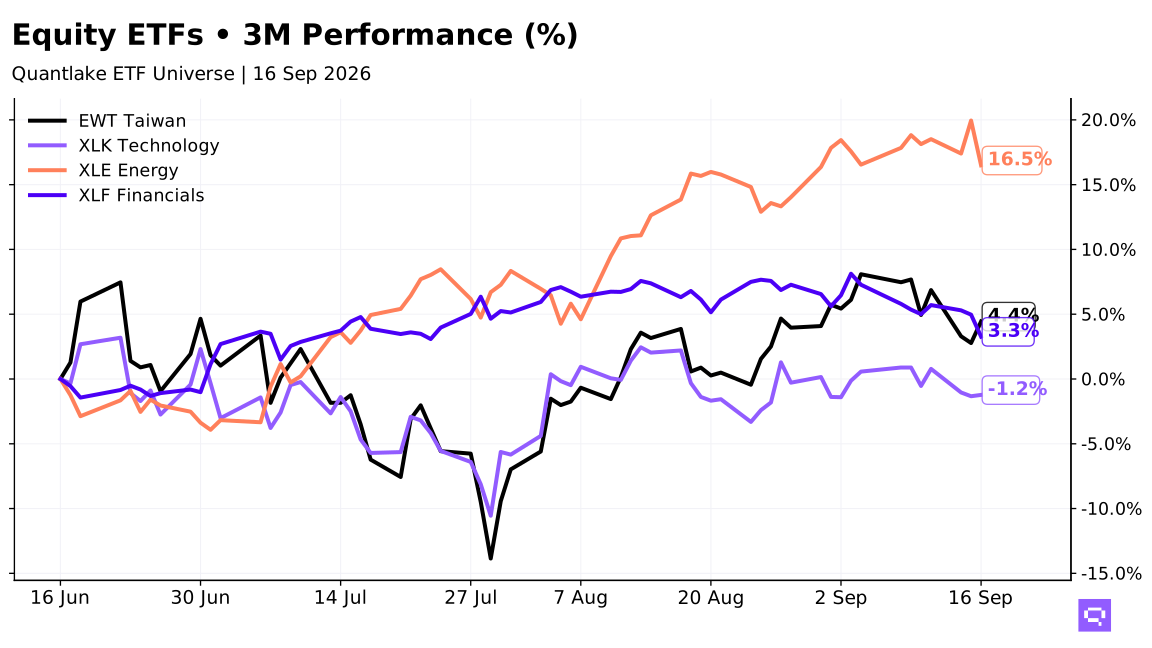
Equity: Tech-leaning equities held up, cyclicals lagged
Movers
Outperformers: Taiwan EWT +1.62% (3M: +4.4%), Technology XLK +0.10% (3M: -1.2%)
Underperformers: Energy XLE -2.88% (3M: +16.5%), Financials XLF -1.62% (3M: +3.3%)
3M Leaderboard
Strong: Energy XLE +16.5%, Healthcare XLV +10.2%, Brazil EWZ +8.9%
Weak: South Korea EWY -14.8%, Utilities XLU -7.7%, Consumer Discretionary XLY -6.8%
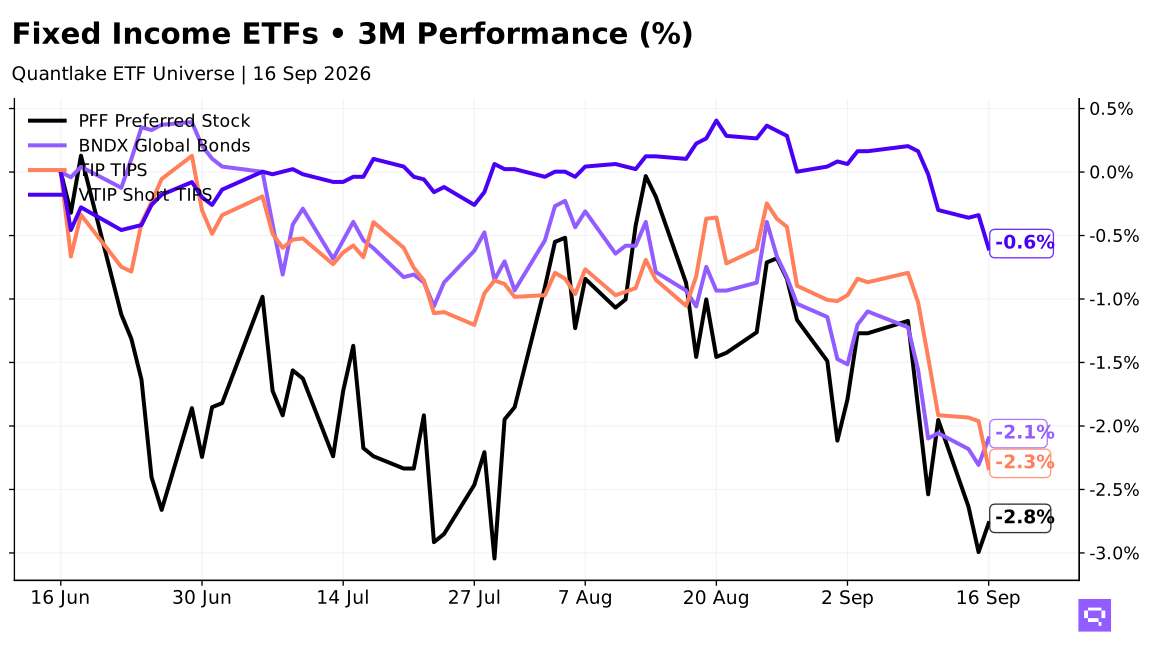
Fixed Income: Preferreds and global bonds led, inflation-linked debt lagged
Movers
Outperformers: Preferred Stock PFF +0.23% (3M: -2.8%), Global Bonds BNDX +0.21% (3M: -2.1%)
Underperformers: TIPS TIP -0.38% (3M: -2.3%), Short TIPS VTIP -0.26% (3M: -0.6%)
3M Leaderboard
Strong: High Yield Bonds JNK -0.5%, High Yield HYG -0.5%, Short TIPS VTIP -0.6%
Weak: Long Treasuries TLT -5.1%, Muni Bonds MUB -3.3%, Investment Grade Credit LQD -3.1%
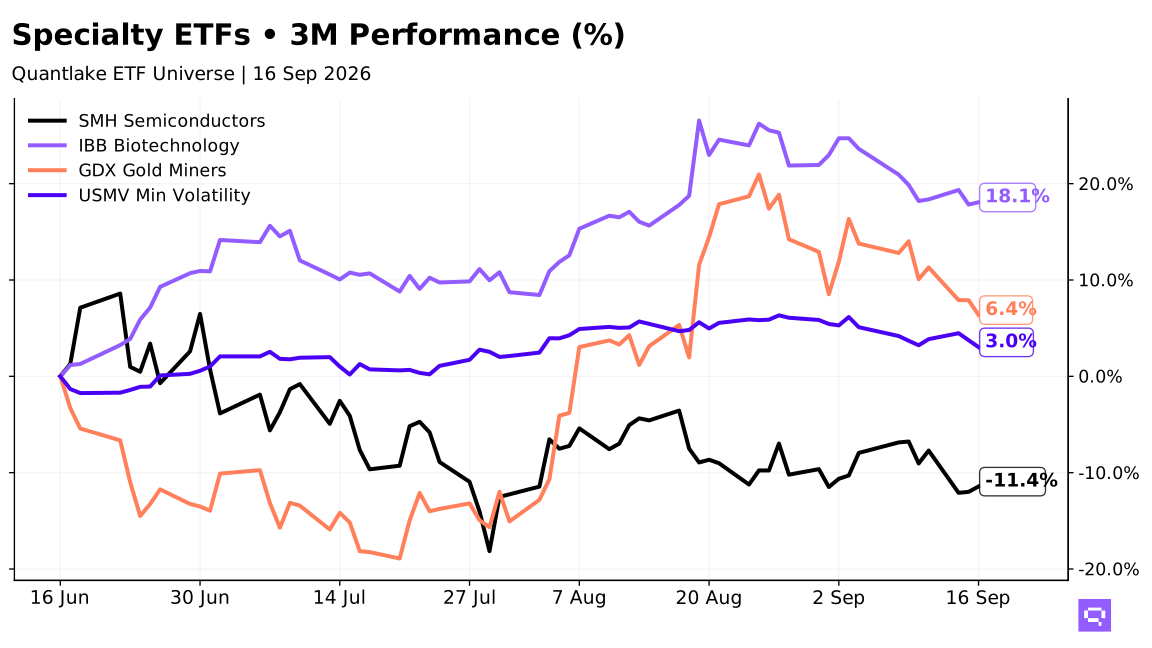
Specialty: Growth niches led, miners and defensives lagged
Movers
Outperformers: Semiconductors SMH +0.64% (3M: -11.4%), Biotechnology IBB +0.20% (3M: +18.1%)
Underperformers: Gold Miners GDX -1.41% (3M: +6.4%), Min Volatility USMV -0.70% (3M: +3.0%)
3M Leaderboard
Strong: Ethereum Trust ETHA +34.1%, Biotechnology IBB +18.1%, Bitcoin Trust IBIT +15.8%
Weak: Clean Energy ICLN -16.8%, Semiconductors SMH -11.4%, Infrastructure PAVE -9.7%
Cross-Asset Read
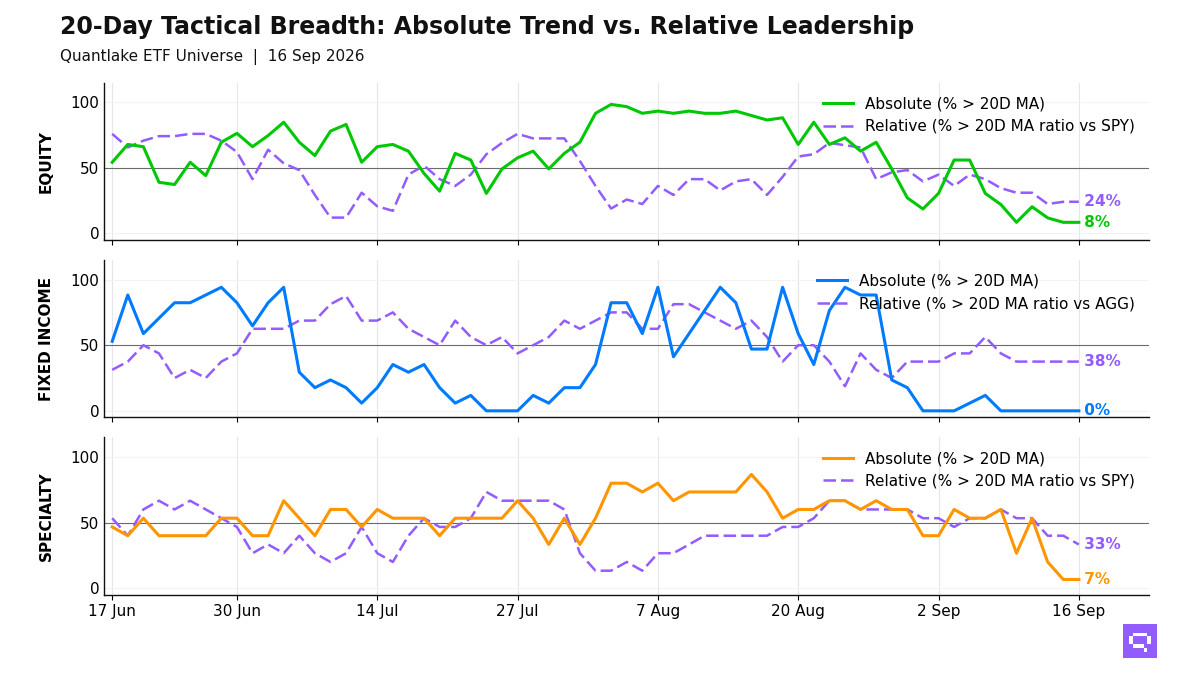
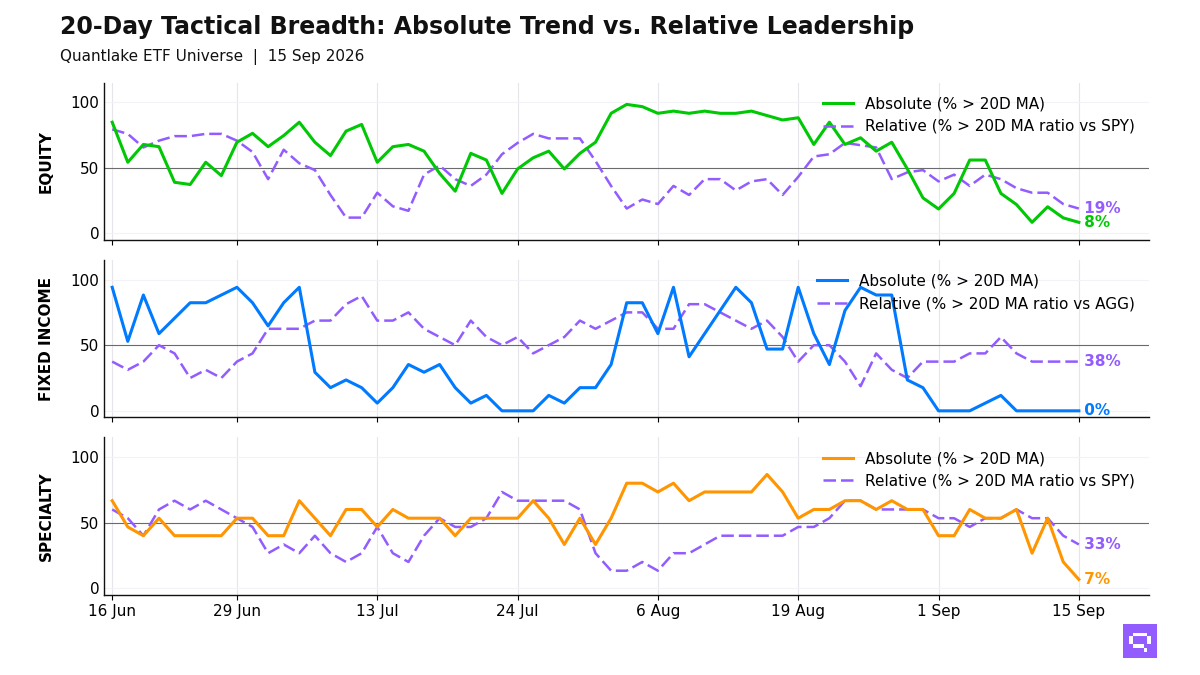
The selective disinflation tilt frames the session: inflation-sensitive equity, rate-linked, and hard-asset exposures weakened together while gains stayed narrow outside that cohort. Structural leadership is mixed across the 3M field, with XLE at +16.5% and XLV at +10.2% in equity, IBB at +18.1% in specialty, and TLT at -5.1% on the fixed-income weak side; today broke the standing 3M lead in XLE, extended it in IBB, and left JNK, HYG, and VTIP near the top of a defensive fixed-income table with 3M returns between -0.5% and -0.6%. Volatility expands in AGG, IEF, and IEI, while compression holds in ACWV, EEM, EWT, FTLS, ICLN, and JEPQ; the cross-asset regime is selective, defensive, and disinflation-leaning.
Romain Gandon
CEO, Quantlake
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice. Past performance is not indicative of future results.