SPY Candlestick Analysis: Forward Returns by Pattern and Sentiment Regime
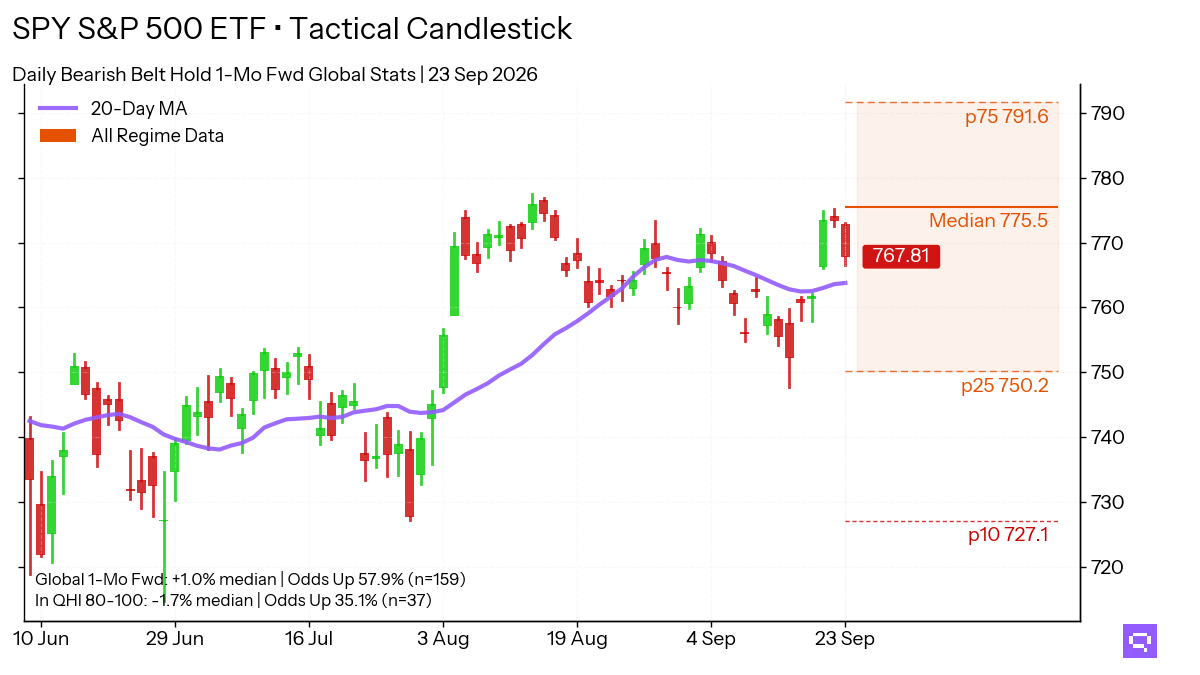
On Wednesday, September 23, the S&P 500 ETF SPY printed a Bearish Belt Hold at $767.81, down 0.72%, with the Quantlake Herd Index (QHI) in Extreme Greed. Across 37 prior occurrences in this regime, the pattern has historically resolved higher one month later 35.1% of the time.
The Bearish Belt Hold is a bearish reversal that opens at the high with a strong real body and shows selling conviction.
SPY Bearish Belt Hold: 1-Month Historical Performance
Across 159 instances since 2009, the pattern resolves higher 57.9% of the time. The median 1-month return is 1.0%, the average is 0.2%, and the annualized Sharpe is 0.18. The base rate leans positive. The edge is narrow. The return distribution leans left, with skew at -0.7 and a tail range from -5.3% to +4.8%. Gains occur more often than losses, and downside outcomes run slightly larger when they occur.
Bearish Belt Hold in QHI Extreme Greed (80-100 pts): Regime-Adjusted Statistics
The Extreme Greed subset contains 37 observations, so the directional count is informative and higher moments carry more uncertainty than the global baseline. SPY's 1-month up rate after this pattern is 35.1% when the QHI registers Extreme Greed, versus 57.9% globally. The median return is -1.7%, the average is -1.4%, and the annualized Sharpe is -1.24. The regime difference is broad because the directional rate, central tendency, and risk-adjusted return all run below the full sample.
The full QHI historical series since September 1, 2009 is available via the Quantlake API for systematic integration. Learn more about the QHI methodology → Data: 23 Sep 2026 · Daily Time Scale.
Bearish Belt Hold: 1-Month Forward Returns by Sentiment Regime
Metric
All regimes
baseline
Extreme Fear *
0-20 pts
Fear
20-40 pts
Neutral *
40-60 pts
Greed
60-80 pts
Extreme Greed
80-100 pts
Occurrences
159
18
36
26
42
37
Up rate
57.9%
94.4%
52.8%
73.1%
57.1%
35.1%
Average return
+0.2%
+2.7%
-0.2%
+1.0%
+0.4%
-1.4%
Median return
+1.0%
+2.6%
+0.2%
+2.0%
+0.7%
-1.7%
Minimum
-11.0%
-1.8%
-11.0%
-6.0%
-9.3%
-8.6%
10th percentile
-5.3%
+1.1%
-5.0%
-3.9%
-3.3%
-6.0%
25th percentile
-2.3%
+1.5%
-2.7%
-1.1%
-1.8%
-4.4%
75th percentile
+3.1%
+3.6%
+3.2%
+3.0%
+3.6%
+2.0%
90th percentile
+4.8%
+5.4%
+4.0%
+3.7%
+5.8%
+3.9%
Maximum
+6.9%
+6.5%
+6.9%
+5.8%
+6.2%
+5.6%
Skew
-0.7
—
-0.8
—
-0.7
-0.0
Excess kurtosis
+0.0
—
+0.5
—
+0.5
-0.8
Sharpe ratio
+0.18
+4.68
-0.16
+1.08
+0.36
-1.24
* fewer than 30 occurrences; treat the column as indicative. Skew and excess kurtosis are withheld below that count. Returns are 1-month forward, in percent. Sharpe is annualised.
Romain Gandon CEO, Quantlake
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice. Past performance is not indicative of future results.
The Quantlake Herd Index (QHI) is a proprietary cross-asset behavioral sentiment composite ranging from 0 to 100 that measures extremes in investor psychology across the U.S. financial system.
It aggregates signals from U.S. equity momentum and breadth, equity market concentration dynamics, credit market risk appetite (high-yield vs investment-grade demand), implied volatility conditions, and credit spread behavior. These inputs are normalized into a single behavioral risk barometer reflecting the balance between risk-averse and risk-on investor behavior.
Because markets are influenced by behavioral biases, sentiment extremes frequently precede mean reversion in forward returns.
QHI Regimes
0–20
Extreme Fear
20–40
Fear
40–60
Neutral
60–80
Greed
80–100
Extreme Greed
Statistical Terms
Median: The midpoint of the return distribution — 50% of outcomes fell above and 50% below this value. Less sensitive to extreme outliers than the average.
p25 / p75 (Interquartile Range): The range within which the middle 50% of historical outcomes fell. p25 marks the 25th percentile (bottom of the range); p75 marks the 75th percentile (top). A tighter range indicates a more predictable pattern; a wide range reflects high dispersion.
p10 / p90 (Tail Interval): The range encompassing the middle 80% of historical outcomes. P10 represents the 10th percentile (the "downside" threshold), while P90 represents the 90th percentile (the "upside" threshold). Unlike the Interquartile Range, this metric captures the shoulders of the distribution, providing a clearer view of potential tail risk and extreme performance potential.
Skew (γ1 — Skewness): Measures the asymmetry of the return distribution. A negative skew (γ1 < 0) signals a left-tailed distribution — most outcomes cluster on the positive side, but the rare negative outcomes can be severely large. A positive skew (γ1 > 0) is the opposite.
Kurt (γ2 — Excess Kurtosis): Measures tail density relative to a normal distribution. A high positive value (Leptokurtic) indicates fat tails — extreme events occur more frequently than a normal distribution would predict. A negative value (Platykurtic) indicates thinner tails.
Mesokurtic: A kurtosis value typically within a range of -0.5 to +0.5, consistent with a normal (Gaussian) distribution. Tail risk is neither elevated nor suppressed relative to standard statistical models.
Gaussian (Normal Distribution): The classic bell-curve distribution. When a pattern's moments are described as "consistent with Gaussian expectations," it means tail risk behaves as standard statistical models would predict — no unusual concentration of extreme outcomes.
Sharpe Ratio (annualised): Measures risk-adjusted return — the average 1-month forward return divided by its standard deviation, scaled to an annual rate (×√12). A ratio above 1.0 indicates strong return per unit of risk; below 0.5 is weak; negative means the average outcome was a loss. It does not capture skewness or tail risk, so it should be read alongside the distribution metrics above.
Share this article
Join our Community of Smarter Investors
Thank you! You're all set!
Oops! Something went wrong while submitting the form.
We use cookies to enhance your browsing experience, provide personalized content and ads, and analyze our traffic. By clicking "Accept All", you consent to our use of cookies.Cookie Policy
We use cookies to enhance your browsing experience, provide personalized content and ads, and analyze our traffic. By clicking "Accept All", you consent to our use of cookies.Cookie Policy